kottke.org posts about economics
I’ve never heard this theory before: L. Frank Baum wrote The Wizard of Oz as an allegory for the 1896 Presidential election, the central issue of which was the monetary concept of bimetallism. Quickly, from Wikipedia, a definition of bimetallism:
Bimetallism is a monetary standard in which the value of the monetary unit is defined as equivalent to certain quantities of two metals, typically gold and silver, creating a fixed rate of exchange between them.
There was much debate in the run-up to the election over how to define the rate between gold and silver in the US. Here’s where The Wizard of Oz comes in:
Dorothy is whipped out of Kansas by a tornado with her little dog “Toto” (short for teetotalers, who made a loud noise yip-yapping but were otherwise ineffective political companions). On her way to the Land of Oz, Dorothy picks up her electoral coalition. First, the Scarecrow, representing western farmers. “He thinks that he has no brains because his head is stuffed with straw. But we soon learn that he is shrewd and capable. He brings to life a major theme of the free silver movement: that the people, the farmer in particular, were capable of understanding the complex theories that underlay the choice of a standard.”
Next, the Tin Man (or Tin Woodman). The working class man, once a true human, is now just a cog in the industrial machine. Piece by piece his human body was replaced by metallic parts. He is now little more than a machine, a heartless (literally) machine. The Populist hope of the era was a grand farmer-labor coalition that never quite solidified — and we still see residual evidence of this hope in the official name of Minnesota’s Democratic Party, the Democratic-Farmer-Labor Party.
The Cowardly Lion, then, was William Jennings Bryan himself. Capable of a great roar — his speeches were legendary — alas, to mix metaphors, he was all bark and no bite.
(via kyle westaway)
Starbucks sells coffee. But you can also think of Starbucks as a bank — and an unregulated one at that. As part of their rewards program, millions of Starbucks customers have preloaded money onto Starbucks cards, essentially loaning the company more than $1 billion at 0% interest.
Starbucks has around $1.6 billion in stored value card liabilities outstanding. This represents the sum of all physical gift cards held in customer’s wallets as well as the digital value of electronic balances held in the Starbucks Mobile App.* It amounts to ~6% of all of the company’s liabilities.
This is a pretty incredible number. Stored value card liabilities are the money that you, oh loyal Starbucks customer, use to buy coffee. What you might not realize is that these balances simultaneously function as a loan to Starbucks. Starbucks doesn’t pay any interest on balances held in the Starbucks app or gift cards. You, the loyal customer, are providing the company with free debt.
See also McDonald’s is a real estate company.
Anne Helen Peterson noticed a bunch of reports about fast food & retail businesses around the US having trouble finding employees, which difficulty the business owners are blaming on lazy American workers whose unemployment benefits have been extended/expanded during the pandemic. But what if, she writes, those benefits are actually providing a safety net to American workers so that they do not need to take terrible jobs for low wages at terrible companies under terrible management? The ‘Capitalism is Broken’ Economy:
Stick with me here, but what if people weren’t lazy — and instead, for the first time in a long time, were able to say no to exploitative working conditions and poverty-level wages? And what if business owners are scandalized, dismayed, frustrated, or bewildered by this scenario because their pre-pandemic business models were predicated on a steady stream of non-unionized labor with no other options? It’s not the labor force that’s breaking. It’s the economic model.
Unemployment benefits have offered a steady paycheck while you figure out your options. Put differently: a version of the safety net that’s been missing from most American employment, and, by extension, the ability to say no. No, I don’t have to work for a restaurant that only gives me my hours three days ahead of time, thus making it nearly impossible to find reliable childcare. No, I don’t have to work clopen shifts. No, I don’t have to expect a job without sick leave or paid time off. No, I don’t have to deal with asshole customers or managers who degrade me without consequence. No, I don’t have to work in a job with significant, accumulating health risks.
Her question near the end of the piece is worth considering: “If a business can’t pay a living wage, should it be a business?”
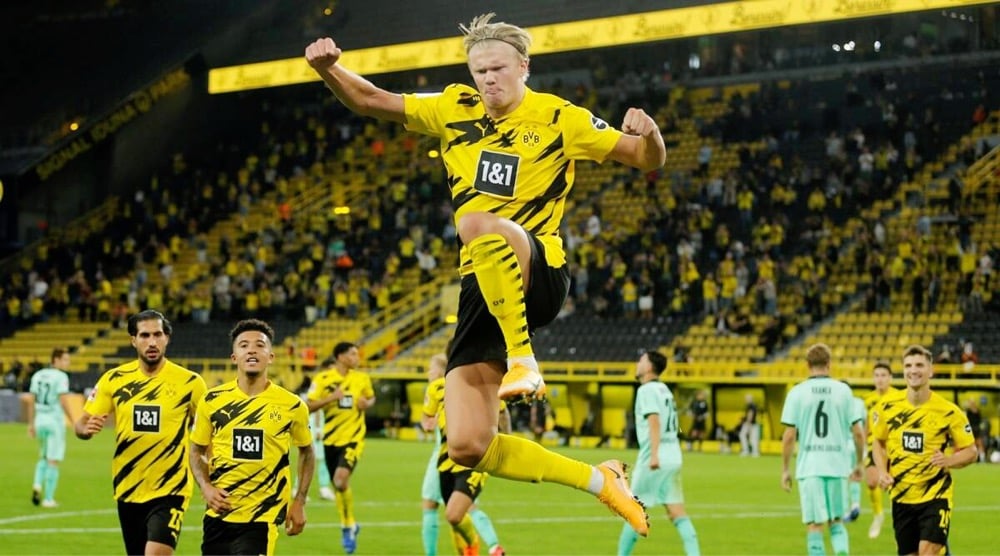
Last week, twelve of the biggest, richest, and best European soccer teams announced they were going to form a new midweek competition called The European Super League. The reaction was swift: fans revolted, soccer governing bodies threatened to kick these teams out of other competitions (with immediate effect, including the Champions League which is presently in the semifinal stage), large-scale condemnation from the press, teams started to back out, and 48 hours after the announcement, the league was all but dead.
So what the hell happened? There have been lots of takes and I obviously haven’t read them all, but here are two I found especially valuable in wrapping my head about the Super League failure and, more importantly, what it can tell us about how power, wealth, community, and attention interact 21 years into this rapidly aging century. First up, Alex Shephard writing for The New Republic: The Existential Crisis That Led to the European Super League Fiasco.
What all of these cultural dinosaurs are confronting, though rarely head on, is the fact that there is no monoculture anymore. They may occupy tremendous cultural space — and a team like Real Madrid is rivaled only by other European soccer teams in the sports world — but it is not and never will be what it was before. The mass appeal these teams enjoyed until fairly recently is not coming back, and it’s not just the fault of Fortnite or FIFA. There are simply too many competitors — and, after all, you can watch the best bits on social media anyways.
And then Ryan O’Hanlon interviewed economist Mark Blyth for his newsletter: How the Spectacular, Comical Failure of the Super League Explains the World.
O’Hanlon: In addition to the various corporate pressures, it really does seem like the fan reaction made a material difference. Do you find that heartening at all?
Blyth: I think it’s heartening in the following sense. It’s emblematic of broader shifts that are going on right now. Basically we’re all struggling to find a capitalism 4.0, and we’re all fed up with capitalism 3.0, and this is a huge example of the limits of capitalism 3.0. This “I own it. It’s my right. I’ll do what I want with it”. Except, no you won’t because there’s such a thing as a public conception of ownership of these assets, even if you formally own them. There are limits to how far you can push this market logic on the social institutions without provoking a reaction. Karl Polanyi, the Hungarian sociologist and historian from the 1940s, wrote that the big fuck-ups of the 19th century and 20th century were attempts to shove markets down people’s throats to the point where they revolted.
In a sense, what you’re seeing here is a classic Polanyian reaction. So I think it’s heartening in that it shows there are limits to how much you can commodify these social goods even if they are nominally private assets. It’s heartening in another way in that they’re gonna have to have a reckoning with these balance sheets. If you’re not Sheikh Mansour and you’re not Roman Abramovich, how are you going to fund Paul Pogba’s ridiculous salary? And it’s just not clear that you are going to, so there may need to be a restructuring, which would be great because the model is there. Look at how the Germans do this. They invest heavily in talent. They invest heavily in youth, they buy, but they buy judiciously. They don’t pay ludicrous salaries. And the funds own 51 percent of the companies. It’s a perfect model, right? Because they’ve got cooperative ownership between the people who are the kind of social owners. And then you’ve got the titular owners who do the investment, and there’s a balance of those interests.
Let me know if there are other Super League pieces out there that I should read — I’ll add them to this post. (Photo above of Erling Haaland because he is a goofy beast and one of the 12 Super League teams is going to pay an absolutely obscene amount of money for him in a few months.)
Writer Ted Chiang (author of the fantastic Exhalation) was recently a guest on the Ezra Klein Show. The conversation ranged widely — I enjoyed his thoughts on superheroes — but his comments on capitalism and technology seem particularly relevant right now. From the transcript:
I tend to think that most fears about A.I. are best understood as fears about capitalism. And I think that this is actually true of most fears of technology, too. Most of our fears or anxieties about technology are best understood as fears or anxiety about how capitalism will use technology against us. And technology and capitalism have been so closely intertwined that it’s hard to distinguish the two.
Let’s think about it this way. How much would we fear any technology, whether A.I. or some other technology, how much would you fear it if we lived in a world that was a lot like Denmark or if the entire world was run sort of on the principles of one of the Scandinavian countries? There’s universal health care. Everyone has child care, free college maybe. And maybe there’s some version of universal basic income there.
Now if the entire world operates according to — is run on those principles, how much do you worry about a new technology then? I think much, much less than we do now. Most of the things that we worry about under the mode of capitalism that the U.S practices, that is going to put people out of work, that is going to make people’s lives harder, because corporations will see it as a way to increase their profits and reduce their costs. It’s not intrinsic to that technology. It’s not that technology fundamentally is about putting people out of work.
It’s capitalism that wants to reduce costs and reduce costs by laying people off. It’s not that like all technology suddenly becomes benign in this world. But it’s like, in a world where we have really strong social safety nets, then you could maybe actually evaluate sort of the pros and cons of technology as a technology, as opposed to seeing it through how capitalism is going to use it against us. How are giant corporations going to use this to increase their profits at our expense?
And so, I feel like that is kind of the unexamined assumption in a lot of discussions about the inevitability of technological change and technologically-induced unemployment. Those are fundamentally about capitalism and the fact that we are sort of unable to question capitalism. We take it as an assumption that it will always exist and that we will never escape it. And that’s sort of the background radiation that we are all having to live with. But yeah, I’d like us to be able to separate an evaluation of the merits and drawbacks of technology from the framework of capitalism.
Echoing some of his other thoughts during the podcast, Chiang also wrote a piece for the New Yorker the other day about how the singularity will probably never come.
Buried deep within Jamie Lauren Keiles’ NY Times article about frequent flyer miles and The Points Guy is this economic observation:
A major reason points-and-miles trips exist is because airlines turn a more stable profit by minting their own currencies than by selling actual airline seats. The flight seems almost ancillary to the financial transaction it enables — a trend across the whole economy, where the selling of goods or services serves to enable the collection of data, the absorption of venture capital funds or the levying of hidden transaction fees. In this scheme, posting to social media, or collecting points and miles, or ordering a taxi or a gyro on your phone, is merely a gesture to keep the whole process in motion. The real moneymaking happens behind the scenes, driven by a series of exchanges where value seems conjured from nothing at all.
But of course, value always comes from somewhere. If you trace the thread back on any one of these businesses, it’s always the same deal: The poor underwrite the fantasies of the middle class, who in turn underwrite the realities of the rich. When credit cards charge high interchange fees, they pass the cost of loyalty programs on to merchants, who in turn pass it back to customers by building the fees into their sticker prices. Those who pay with credit can earn it back in points. Those who pay with debit or cash wind up subsidizing someone else’s free vacation. According to a 2010 policy paper by economists at the Federal Reserve Bank of Boston, the average cash-using household paid $149 over the course of a year to card-using households, while each card-using household received $1,133 from cash users, partially in the form of rewards. It remains a regressive transfer to this day.
Emphasis of the second to last sentence is mine.
Trickle-down economics is the economic theory that lowering taxes on the wealthy and on businesses will stimulate business investment to the long-term benefit of society. The idea is that by sprinkling a huge amount of money into the bank accounts and stock portfolios of the wealthy, a portion of that money will “trickle down” to everyone else. Despite ample evidence that it hasn’t worked, trickle-down has been an economic driver for discussions about taxes in the US since at least the Reagan administration. The newest research that argues that tax cuts for the rich don’t work for anyone other than the rich comes in the form of working paper by David Hope of the London School of Economics and Julian Limberg of King’s College London called The Economic Consequences of Major Tax Cuts for the Rich. From the press release:
Our results show that…major tax cuts for the rich increase the top 1% share of pre-tax national income in the years following the reform. The magnitude of the effect is sizeable; on average, each major reform leads to a rise in top 1% share of pre-tax national income of 0.8 percentage points. The results also show that economic performance, as measured by real GDP per capita and the unemployment rate, is not significantly affected by major tax cuts for the rich. The estimated effects for these variables are statistically indistinguishable from zero.
And the authors’ conclusion:
Our results have important implications for current debates around the economic consequences of taxing the rich, as they provide causal evidence that supports the growing pool of evidence from correlational studies that cutting taxes on the rich increases top income shares, but has little effect on economic performance.
Limberg connected the results of the research to post-pandemic economic recovery:
Our results might be welcome news for governments as they seek to repair the public finances after the COVID-19 crisis, as they imply that they should not be unduly concerned about the economic consequences of higher taxes on the rich.
Former US Labor Secretary Robert Reich agrees that the US should tax the rich to invest in public infrastructure.
The practical alternative to trickle-down economics might be called build-up economics. Not only should the rich pay for today’s devastating crisis but they should also invest in the public’s long-term wellbeing. The rich themselves would benefit from doing so, as would everyone else.
At one time, America’s major political parties were on the way to embodying these two theories. Speaking to the Democratic national convention in 1896, populist William Jennings Bryan noted: “There are two ideas of government. There are those who believe that, if you will only legislate to make the well-to-do prosperous, their prosperity will leak through on those below. The Democratic idea, however, has been that if you legislate to make the masses prosperous, their prosperity will find its way up through every class which rests upon them.”
Build-up economics reached its zenith in the decades after the second world war, when the richest Americans paid a marginal income tax rate of between 70% and 90%. That revenue helped fund massive investment in infrastructure, education, health and basic research — creating the largest and most productive middle class the world had ever seen.
In a piece for the NY Times called What Is Owed, Nikole Hannah-Jones argues that because of its sanction of slavery and subsequent legalized racial segregation and discrimination, it is time for the United States government to pay its debt to Black Americans in form of reparations.
To summarize, none of the actions we are told black people must take if they want to “lift themselves” out of poverty and gain financial stability — not marrying, not getting educated, not saving more, not owning a home — can mitigate 400 years of racialized plundering. Wealth begets wealth, and white Americans have had centuries of government assistance to accumulate wealth, while the government has for the vast history of this country worked against black Americans doing the same.
“The cause of the gap must be found in the structural characteristics of the American economy, heavily infused at every point with both an inheritance of racism and the ongoing authority of white supremacy,” the authors of the Duke study write. “There are no actions that black Americans can take unilaterally that will have much of an effect on reducing the wealth gap. For the gap to be closed, America must undergo a vast social transformation produced by the adoption of bold national policies.”
This piece is one of the best things I’ve read this year. It is clear, focused, powerful, and persuasive. There is no amount of money that anyone could ever pay to make up for the 400+ years of absolute shit rained down on Black people by the United States of America and its precursors, but nevertheless, reparations are the only just and moral way forward for the United States.
P.S. Here’s the Duke study mentioned in the excerpt above: What We Get Wrong About Closing the Racial Wealth Gap. And the book containing a detailed plan for reparations mentioned by Hannah-Jones is From Here to Equality: Reparations for Black Americans in the Twenty-First Century (ebook).
Update: Terry Gross interviewed Hannah-Jones on Fresh Air about reparations.
I think that reparations can’t just be any one thing. I think that you have to have targeted investment in Black communities and Black schools that have been generationally under-resourced. You certainly need to have a commitment to strong enforcement of existing civil rights laws, because reparations don’t do any good if you’re still facing rampant employment and housing and educational discrimination. But the center of any reparations program has to be cash payments. The only thing that closes a wealth gap is money.
For Slate’s 2015 podcast series The History of American Slavery, Andrew Kahn created an interactive visualization of the 20,000+ voyages that made up the Atlantic slave trade that lasted 315 years. A video of the interactive map is embedded above.
As we discussed in Episode 2 of Slate’s History of American Slavery Academy, relative to the entire slave trade, North America was a bit player. From the trade’s beginning in the 16th century to its conclusion in the 19th, slave merchants brought the vast majority of enslaved Africans to two places: the Caribbean and Brazil. Of the more than 10 million enslaved Africans to eventually reach the Western Hemisphere, just 388,747 — less than 4 percent of the total — came to North America. This was dwarfed by the 1.3 million brought to Spanish Central America, the 4 million brought to British, French, Dutch, and Danish holdings in the Caribbean, and the 4.8 million brought to Brazil.
Roughly 400,000 enslaved Africans were brought to the United States before the practice was banned in 1808. The ban was mostly (but not entirely) enforced and yet in 1860, the population of enslaved persons was almost 4 million in the South. That’s because the 1808 ban, according to Ned & Constance Sublette’s book The American Slave Coast: A History of the Slave-Breeding Industry, was a form of trade protectionism that protected the forced breeding of enslaved peoples by American slaveowners. From a review of the book:
In fact, most American slaves were not kidnapped on another continent. Though over 12.7 million Africans were forced onto ships to the Western hemisphere, estimates only have 400,000-500,000 landing in present-day America. How then to account for the four million black slaves who were tilling fields in 1860? “The South,” the Sublettes write, “did not only produce tobacco, rice, sugar, and cotton as commodities for sale; it produced people.” Slavers called slave-breeding “natural increase,” but there was nothing natural about producing slaves; it took scientific management. Thomas Jefferson bragged to George Washington that the birth of black children was increasing Virginia’s capital stock by four percent annually.
Here is how the American slave-breeding industry worked, according to the Sublettes: Some states (most importantly Virginia) produced slaves as their main domestic crop. The price of slaves was anchored by industry in other states that consumed slaves in the production of rice and sugar, and constant territorial expansion. As long as the slave power continued to grow, breeders could literally bank on future demand and increasing prices. That made slaves not just a commodity, but the closest thing to money that white breeders had. It’s hard to quantify just how valuable people were as commodities, but the Sublettes try to convey it: By a conservative estimate, in 1860 the total value of American slaves was $4 billion, far more than the gold and silver then circulating nationally ($228.3 million, “most of it in the North,” the authors add), total currency ($435.4 million), and even the value of the South’s total farmland ($1.92 billion). Slaves were, to slavers, worth more than everything else they could imagine combined.
You can read more about the economics of slavery in this post from 2016, including how American banks sold bonds that used enslaved persons as collateral to international investors. (via open culture)
In this video for NPR, Gene Demby summarizes the history of housing segregation in America and how it’s a factor for current differences in health (poorer), wealth (much less), education (underfunded), and policing (much more aggressive) for Black communities in US cities.
If you look at the way housing segregation works in America, you can see how things ended up this way. Once you see it, you won’t be able to unsee it.
When you’re talking about housing policy in America, Kimberly Jones’ Monopoly analogy starts to sound a lot less metaphorical and more literal: if Black people cannot buy houses or can only buy houses on certain streets, they will not be able to build wealth like others can.
For more on housing segregation, check out historian Richard Rothstein’s The Color of Law: A Forgotten History of How Our Government Segregated America. From a 2017 interview with Rothstein:
The federal government pursued two important policies in the mid-20th century that segregated metropolitan areas. One was the first civilian public housing program which frequently demolished integrated neighborhoods in order to create segregated public housing.
The second program that the federal government pursued was to subsidize the development of suburbs on a condition that they be only sold to white families and that the homes in those suburbs had deeds that prohibited resale to African-Americans. These two policies worked together to segregate metropolitan areas in ways that they otherwise would never have been segregated.
Rothstein talked about the book with Ta-Nehisi Coates during a conversation at Politics and Prose Bookstore.
Update: This is excellent: you can explore the maps created by the federal government’s Home Owners’ Loan Corporation at Mapping Inequality by the University of Richmond’s Digital Scholarship Lab.
These grades were a tool for redlining: making it difficult or impossible for people in certain areas to access mortgage financing and thus become homeowners. Redlining directed both public and private capital to native-born white families and away from African American and immigrant families. As homeownership was arguably the most significant means of intergenerational wealth building in the United States in the twentieth century, these redlining practices from eight decades ago had long-term effects in creating wealth inequalities that we still see today.
(via @masonadams)
Do me a favor and take about 7 minutes to watch author Kimberly Jones’ off-the-cuff “rant” (her words) about how rioting and looting fit within the larger narrative of the economic oppression of Black people in America. I’ve never heard the long, shameful, and deadly history of white supremacy in America summed up any better or more succinctly than Jones does here. The Monopoly analogy in particular is fantastic.
When they say “Why do you burn down the community? Why do you burn down your own neighborhood?” It’s not ours! We don’t own anything! We don’t own anything! Trevor Noah said it so beautifully last night: There’s a social contract that we all have — that if you steal or if I steal, then the person who is the authority comes in and they fix the situation. But the person who fixes the situation is killing us! So the social contract is broken. And if the social contract is broken, why the fuck do I give a shit about burning the fucking Football Hall of Fame, about burning the fucking Target? You broke the contract when you killed us in the streets and didn’t give a fuck! You broke the contract when for 400 years we played your game and built your wealth!
Update: Jones has signed a deal with Henry Holt and Company to write two books, one of which will be called “How We Can Win” and will be based on the video above.
Update: How We Can Win will be out in November and is now available for preorder.
From an April 17th Facebook post by Paul Field, a succinct summary of how the pandemic exposes American deficiencies. It’s tough to not just quote the whole thing, so here’s the beginning:
Everyone is entitled to their own opinion, but you need to know how silly you look if you post some variation of, “Welcome to Socialism…”
You are not seeing Socialism. What you are seeing is one of the wealthiest, geographically advantaged, productive capitalist societies in the world flounder and fail at its most basic test. Taking care of its people.
This crisis is not about the virus.
This crisis is about the massive failure of our, “Booming economy,” to survive even modest challenges. It is about the market dissonance of shortages in stores, even as farmers/producers destroy unused crops and products. This crisis is about huge corporations needing an emergency bailout within days of the longest Bull Market in our history ending and despite the ability to borrow with zero percent interest rates.
The pandemic has revealed that American democracy and our economic system is extremely fragile. Ok, unless you’re wealthy, in which case you’re going to be fine, all part of the plan, etc.
This too-short profile of Pulitzer Prize-winning journalist Laurie Garrett, who has been writing about epidemics since the 90s, is closer to my personal feelings as to how the pandemic plays out in the US than almost anything else I’ve read.
But she can’t envision that vaccine anytime in the next year, while Covid-19 will remain a crisis much longer than that.
“I’ve been telling everybody that my event horizon is about 36 months, and that’s my best-case scenario,” she said.
“I’m quite certain that this is going to go in waves,” she added. “It won’t be a tsunami that comes across America all at once and then retreats all at once. It will be micro-waves that shoot up in Des Moines and then in New Orleans and then in Houston and so on, and it’s going to affect how people think about all kinds of things.”
They’ll re-evaluate the importance of travel. They’ll reassess their use of mass transit. They’ll revisit the need for face-to-face business meetings. They’ll reappraise having their kids go to college out of state.
Much of the federal government’s response has been to help big business, and the wealthy are going to have opportunities to not only ride out the storm more easily but to take advantage:
If America enters the next wave of coronavirus infections “with the wealthy having gotten somehow wealthier off this pandemic by hedging, by shorting, by doing all the nasty things that they do, and we come out of our rabbit holes and realize, ‘Oh, my God, it’s not just that everyone I love is unemployed or underemployed and can’t make their maintenance or their mortgage payments or their rent payments, but now all of a sudden those jerks that were flying around in private helicopters are now flying on private personal jets and they own an island that they go to and they don’t care whether or not our streets are safe,’ then I think we could have massive political disruption.”
I could quote something from just about every paragraph, but for now I’ll just do one more excerpt and you can go and read the rest.
Garrett recounted her time at Harvard. “The medical school is all marble, with these grand columns,” she said. “The school of public health is this funky building, the ugliest possible architecture, with the ceilings falling in.”
“That’s America?” I asked.
“That’s America,” she said.
See also Dave Eggers’ pandemic Q&A, which shares a certain pessimistic honesty with Garrett’s thoughts.
Using data from the Correlates of War Project and the Stockholm International Peace Research Institute, this bar chart race shows the annual military spending of the world’s top spending countries from the start of WWI in 1914 to 2018. See also military spending info from Our World in Data.
In early March, Dr. Caroline Schulman was responsible for calling patients at her hospital to tell them they had tested positive for Covid-19. She shared some of her experiences in a piece for Stat.
Erik lives with his entire family in a one-room rental house with eight other occupants. He didn’t understand the precautions for preventing the spread of Covid-19 and had regularly been socializing in the apartment. He kept asking how to file for unemployment and how to isolate the household when the house itself could barely hold those living in it.
Jeff lives alone. He has a chronic blood condition and is struggling to get by. A few hours before we talked, he had resumed his job as a ride share driver because he needed to make ends meet.
Angela is 40 years old and has one of the preexisting conditions that put people at high risk for serious complications of Covid-19. When we spoke, she told me that she was feeling better, but that her home life was difficult. Her children had returned home after Mayor Muriel Bowser issued a stay-at-home order for the District of Columbia. She asked her kids to take precautions, but they continued to leave the house often. One son brought home his girlfriend, who had a cough, and displaced Angela from her room. She was unable to make an appointment with her primary doctor and couldn’t afford her medical supplies because of insurance issues. When I spoke with her, she sounded well and had no classic symptoms, but something didn’t sound right. I arranged a televisit that afternoon to have her evaluated more closely. By the time she got the call two hours later, she was so short of breath she could barely speak. When an ambulance arrived to take her to the hospital, her oxygen levels were dangerously low.
Reading through these stories, I just kept thinking about the measures that are going to be necessary if we’re going to safely restart public life in America — hygiene, mask wearing, some social distancing, and eventually a vaccine — and how our collective safety is going to depend on individuals doing the right thing. And most people will. But it’s clear that, especially without coherent national leadership & economic support, some people will be unable to take the necessary precautions for economic reasons and others won’t because they don’t understand why these measures are necessary, don’t trust science, or a dozen other reasons.
Newer posts
Older posts
Socials & More